
Payments
UBX Editorial6 min read
The quiet work of interoperability
When a customer of one bank withdraws cash from another bank's ATM, a lot has to agree in under a second. Shared infrastructure is how a financial system starts behaving like a network.
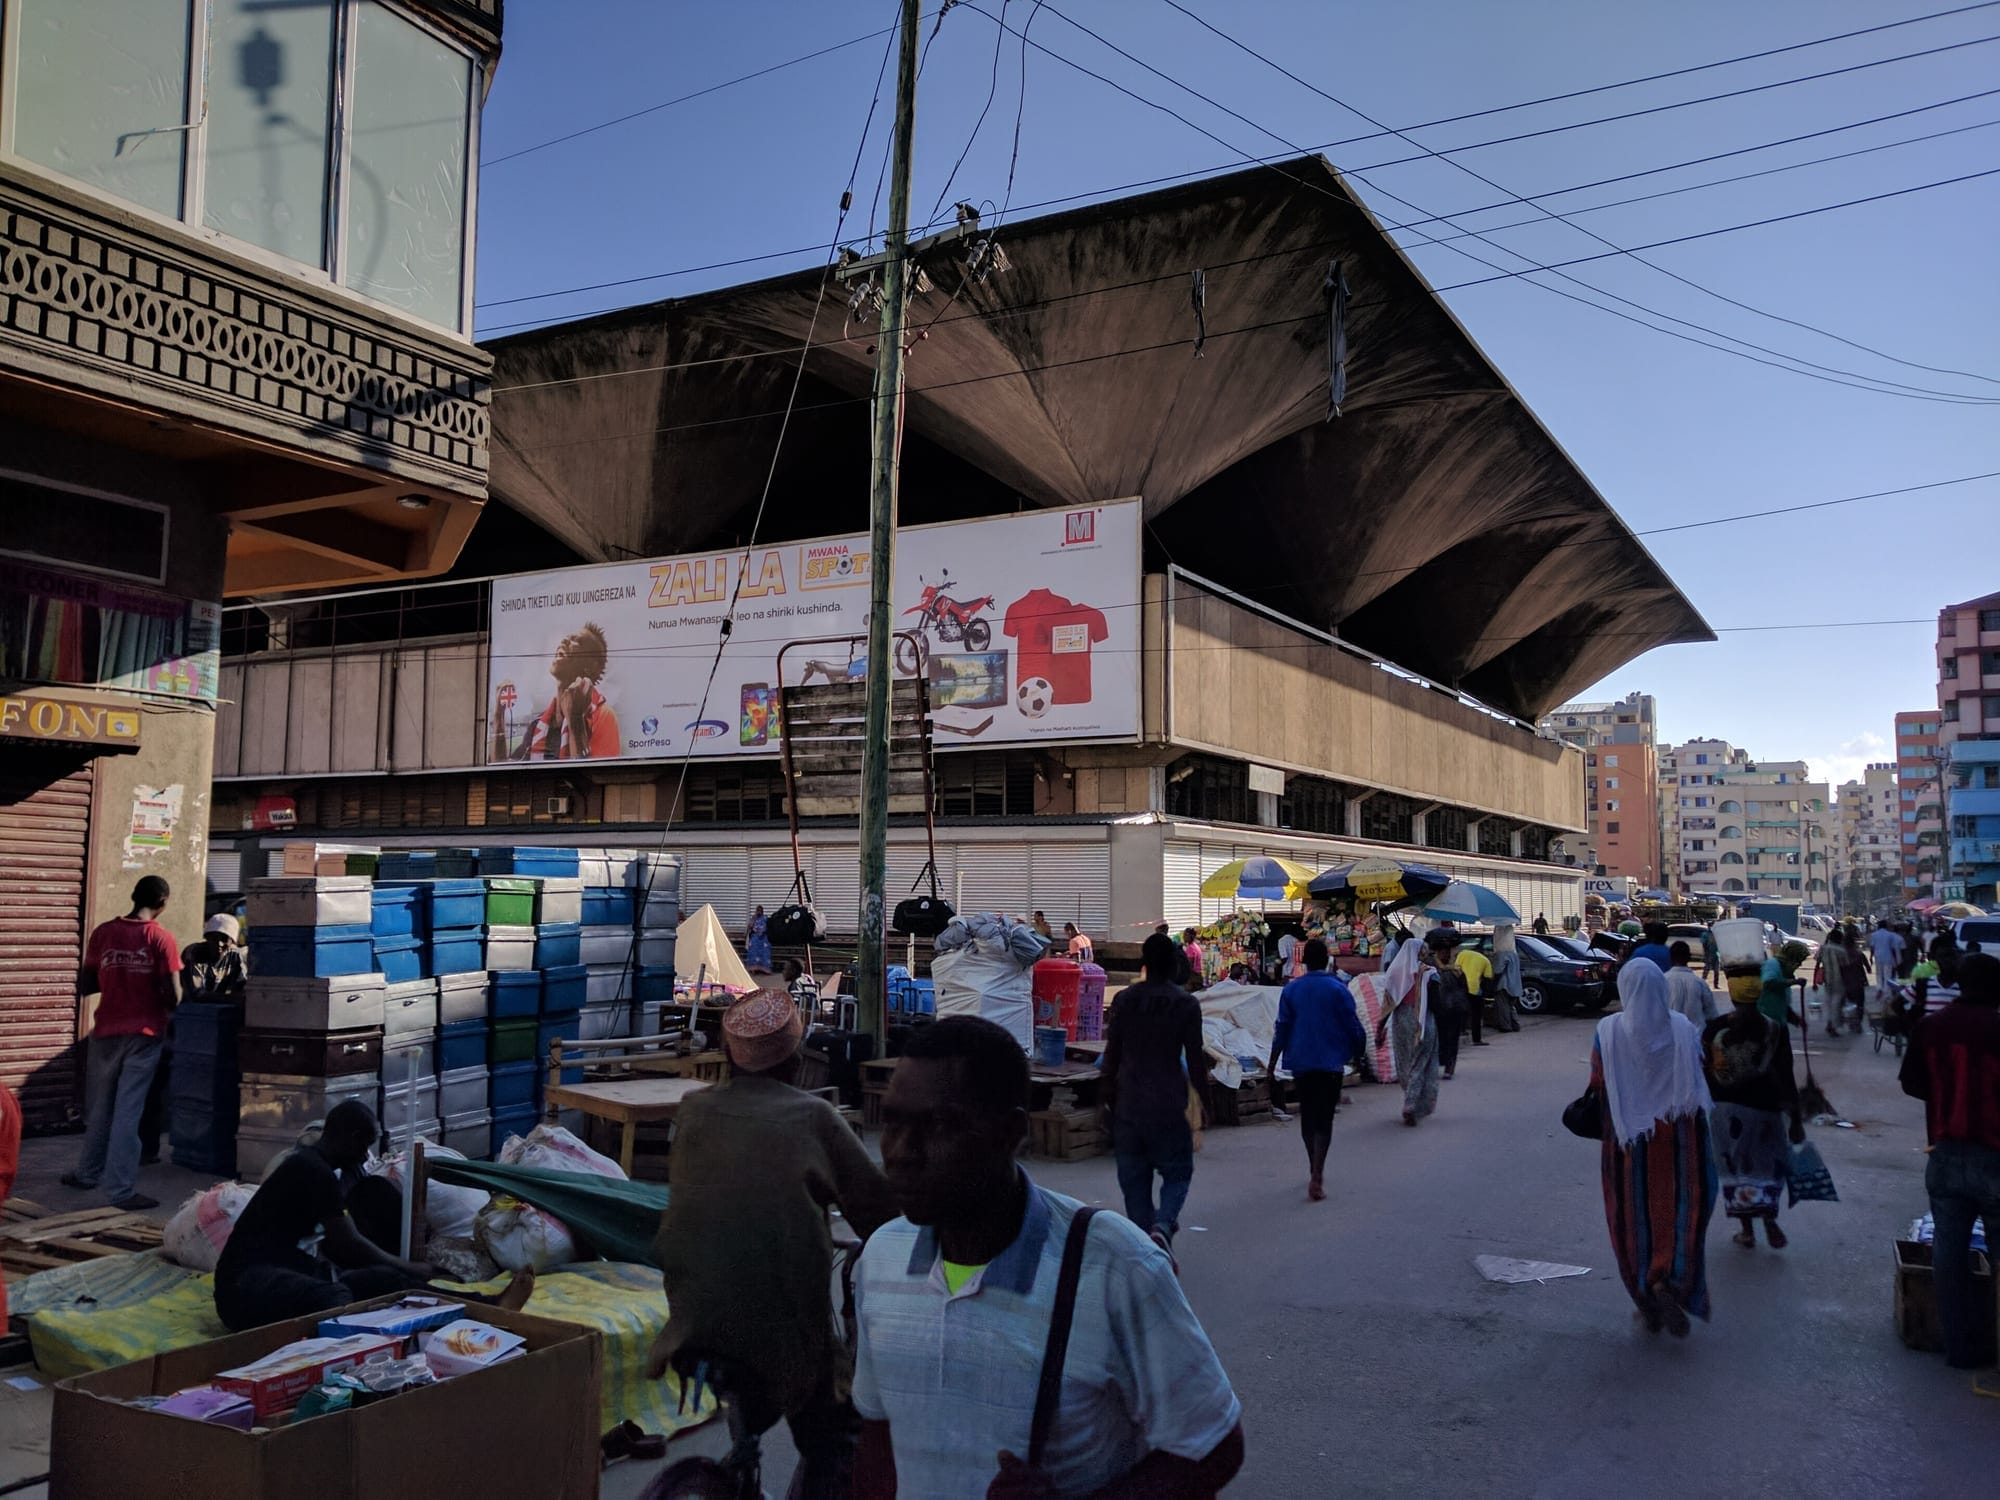
Traders and shoppers on the street outside Kariakoo market in the morning
Demonstration article — placeholder editorial content
Interoperability rarely makes headlines. It is the absence of friction — the moment a card works at a terminal it has never met, or an agent in a market can serve a customer of a bank with no branch nearby. Behind that moment sits a set of shared agreements: message formats, settlement rules, security controls and an operator trusted by every participant.
For institutions, the logic is simple. Building a national network of ATMs or agents alone is expensive and slow. Sharing one multiplies reach for every member while each keeps its own customer relationships.
A switch is a public good with private owners
A shared switch is infrastructure in the way a road is. It works best when it is neutral, reliable and boring. The interesting decisions are about governance: who sets the rules, how disputes are resolved and how new participants — cooperatives, fintechs, wallets — join without weakening the whole.
“The best payment infrastructure is the kind customers never have to think about.”
The next phase of interoperability is less about connecting more machines and more about connecting more kinds of institutions — so that savings groups, merchants and public agencies sit on the same rails as banks.